
Kolkata (West Bengal) [India], November 3: Kolkata-based flexible packaging maker is raising money for working capital, debt repayment and new machines on NSE Emerge; issue closes November 04, 202
Key highlights
- Issue opened November 2, 2026 and closes November 4, 2026; shares are proposed to list on NSE Emerge, with listing expected on or about November 9, 2026.
- Price band: ₹88 to ₹94 per share (face value ₹10); lot size 1,200 shares.
- Offer of up to 60,30,000 shares: fresh issue of up to 54,26,400 shares plus an offer for sale (OFS) of up to 6,03,600 shares by promoter Sethsawaria Poly Fab LLP.
- Issue size works out to roughly ₹56.68 Cr*;
- FY26 revenue stood at ₹115.14 crore, registering a 42.11% year-on-year growth compared to FY25. Profit After Tax (PAT) stood at ₹10.96 crore, reflecting approximately 140% year-on-year growth.
- No anchor investors for this issue.
*calculated at the upper price band
The offer
Vedant Poly Fabs Limited, a Barasat (West Bengal)-based maker of flexible packaging materials, opened its initial public offer on Monday. The company has set a price band of ₹88–94 per share, according to its Red Herring Prospectus (RHP) dated October 27, 2026.
At the band, a retail investor needs a minimum of two lots of 2,400 shares, or about ₹2,11,200/-at the floor price and ₹2,25,600 at the cap price.
The offer comprises a fresh issue of up to 54,26,400 equity shares (₹51.01 Cr, calculated at upper price band) and an OFS of up to 6,03,600 shares (₹5.67 Cr, calculated at upper price band). The company will not receive any money from the OFS. The offer is about 29.9% of the post-issue paid-up capital.
Of the net offer, not more than 50% is for qualified institutional buyers, at least 15% for non-institutional investors and at least 35% for retail investors. A reserved portion of up to 3,04,800 shares is earmarked for the market maker, Giriraj Stock Broking. Affinity Global Capital Market is the sole book running lead manager and Cameo Corporate Services is the registrar.
Tentative timetable: the issue closes November 4, 2026; refunds and credit of shares to demat accounts are expected on or about November 6, 2026; trading is expected to begin on or about November 9, 2026.
What does the company do?
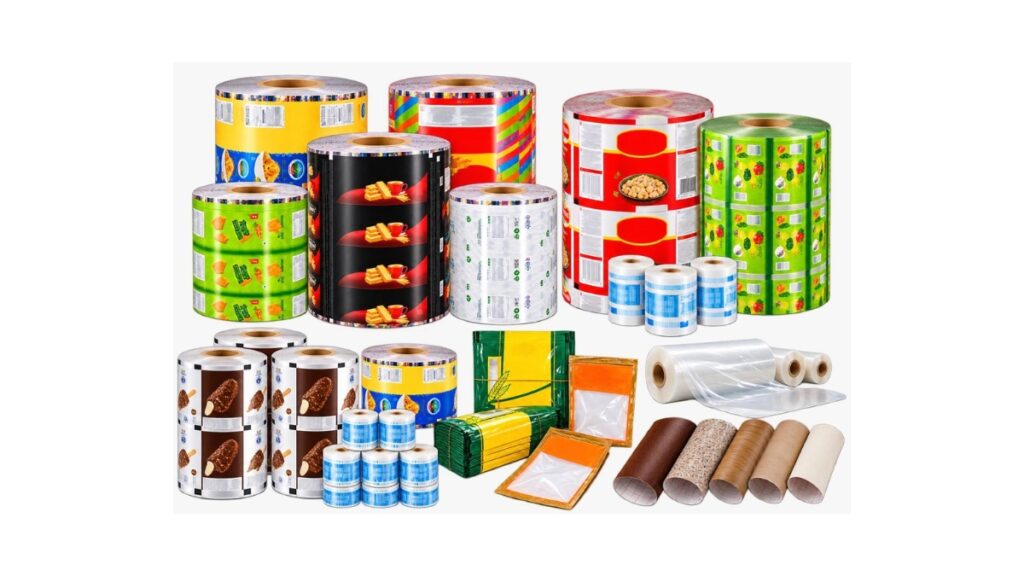
Incorporated in December 2018 and converted into a public company in 2025, Vedant Poly Fabs makes multilayer films (3-layer and 5-layer), shrink films, barrier films, printed laminates, and milk and oil pouches. Its products are used by food and beverage, dairy and other consumer-goods companies.
The company works on a business-to-business model and manufacturer to customer specifications on size, thickness, composition and printing. Its in-house capabilities span multilayer extrusion, CI flexo and rotogravure printing, lamination, slitting and pouching at a single facility. West Bengal is its principal market, though it supplies customers across India.
The company is led by Chairman and Managing Director Pankaj Kumar Maheshwari. The board has three executive directors and three independent directors, two of the independent director are women.
Financials: fast growth, sharply higher margins
The company’s numbers have scaled quickly over the past three years.
| ₹ lakh | FY24 | FY25 | FY26 | Apr–Jun 2026* |
|---|---|---|---|---|
| Revenue from operations | 4,953.46 | 8,102.12 | 11,513.91 | 3,028.78 |
| Operating EBITDA | 128.59 | 774.24 | 1,900.12 | 659.11 |
| Operating EBITDA margin | 2.60% | 9.56% | 16.50% | 21.76% |
| Profit after tax | 63.59 | 456.06 | 1,096.62 | 347.81 |
| PAT margin | 1.28% | 5.63% | 9.52% | 11.48% |
*Three-month stub period; not annualised and not comparable with full-year figures.
Revenue grew about 64% in FY25 and about 42% in FY26, a roughly 52% compound annual rate over two years. Operating EBITDA margin has widened from 2.60% in FY 2023–24 to 16.50% in FY 2025–26, and the company says its revenue mix has tilted towards manufacturing segments. FY26 return on equity stood at 38.03% and return on capital employed at 30.65%, while net worth was ₹42.26 crore at March 31, 2026.
Utilization of the proceeds
From the fresh issue, the company plans to spend:
- ₹24.61 crore on incremental working capital (against a total estimated FY27 working capital requirement of ₹68.47 crore).
- ₹8.00 crore on prepaying or repaying borrowings.
- ₹6.51 crore on plant and machinery at its existing facility.
- The balance on general corporate purposes and offer expenses.
The company’s installed capacity was 88.5 lakh kg in FY26 and 1.10 crore kg* for the June 2026 period, with utilisation at about 71.64% in FY26. The planned new machinery is estimated to take capacity to 1.32 crore kg a year. Brickwork Ratings is the monitoring agency for the use of proceeds.
Shareholding
Promoters hold 98% of the company before the issue, with Sethsawaria Poly Fab LLP alone at 90%; the promoter group holds the remaining 2%, and public shareholders hold a negligible stake. The LLP’s weighted average cost of acquisition is ₹25.93 per share. After the issue, promoters’ holding is expected to fall to roughly 70.08%, going by the offer structure (our calculation).
*capacity is taken on an annualized basis
Risks to weigh
The RHP flags several issues investors should read closely:
- Customer concentration: the top ten customers accounted for 69.64% of sales in FY26 and 79.33% in the April–June 2026 period, up from 13.49% in FY24. Two customers each contributed about 23% of stub-period sales.
- Related-party dealings: related-party transactions were 41% of revenue in FY26 and 26% in the stub period. One related party, Sethsawaria Poly Fab LLP, was among the larger customers, and the company has undertaken to route such sales directly going forward. Lakhotia Packwell, a top supplier, accounted for 47% of FY26 purchases.
- Verbal orders: the company generally receives orders verbally, without formal purchase orders or long-term contracts, and says it is moving to record an order book against purchase orders.
- Geographic concentration: a significant share of revenue comes from West Bengal.
- Raw material dependence: the business relies on a limited set of suppliers and is exposed to input price swings.
- SME-platform liquidity: NSE Emerge shares can be thinly traded, and the RHP notes there is no assurance of active or sustained trading after listing.
- Working Capital Intensity: The quick ratio remained below 1.00 during FY 2023–24 to FY 2025–26, while the Net Capital Turnover Ratio declined from 14.17 in FY 2023–24 to 8.37 in FY 2025–26, indicating increased working capital requirements as the business expanded.
The bottom line
Vedant Poly Fabs offers a small-ticket packaging play with strong growth and improving margins, at a valuation that looks moderate against peers on post-issue numbers. Against that, the business is concentrated in a few customers and related parties, relies on verbal orders, and will trade on the SME platform, where liquidity and volatility can be a concern.
If you object to the content of this press release, please notify us at pr.error.rectification@gmail.com. We will respond and rectify the situation within 24 hours.